hire companies
Speedy Hire lifts hire revenue 7.4% as net debt climbs to £166.1m
The tool and equipment hirer reported half-year revenue of £211.6m and adjusted EBITDA up 10.3%, while net debt rose and it began a review of its portfolio and capital intensity.
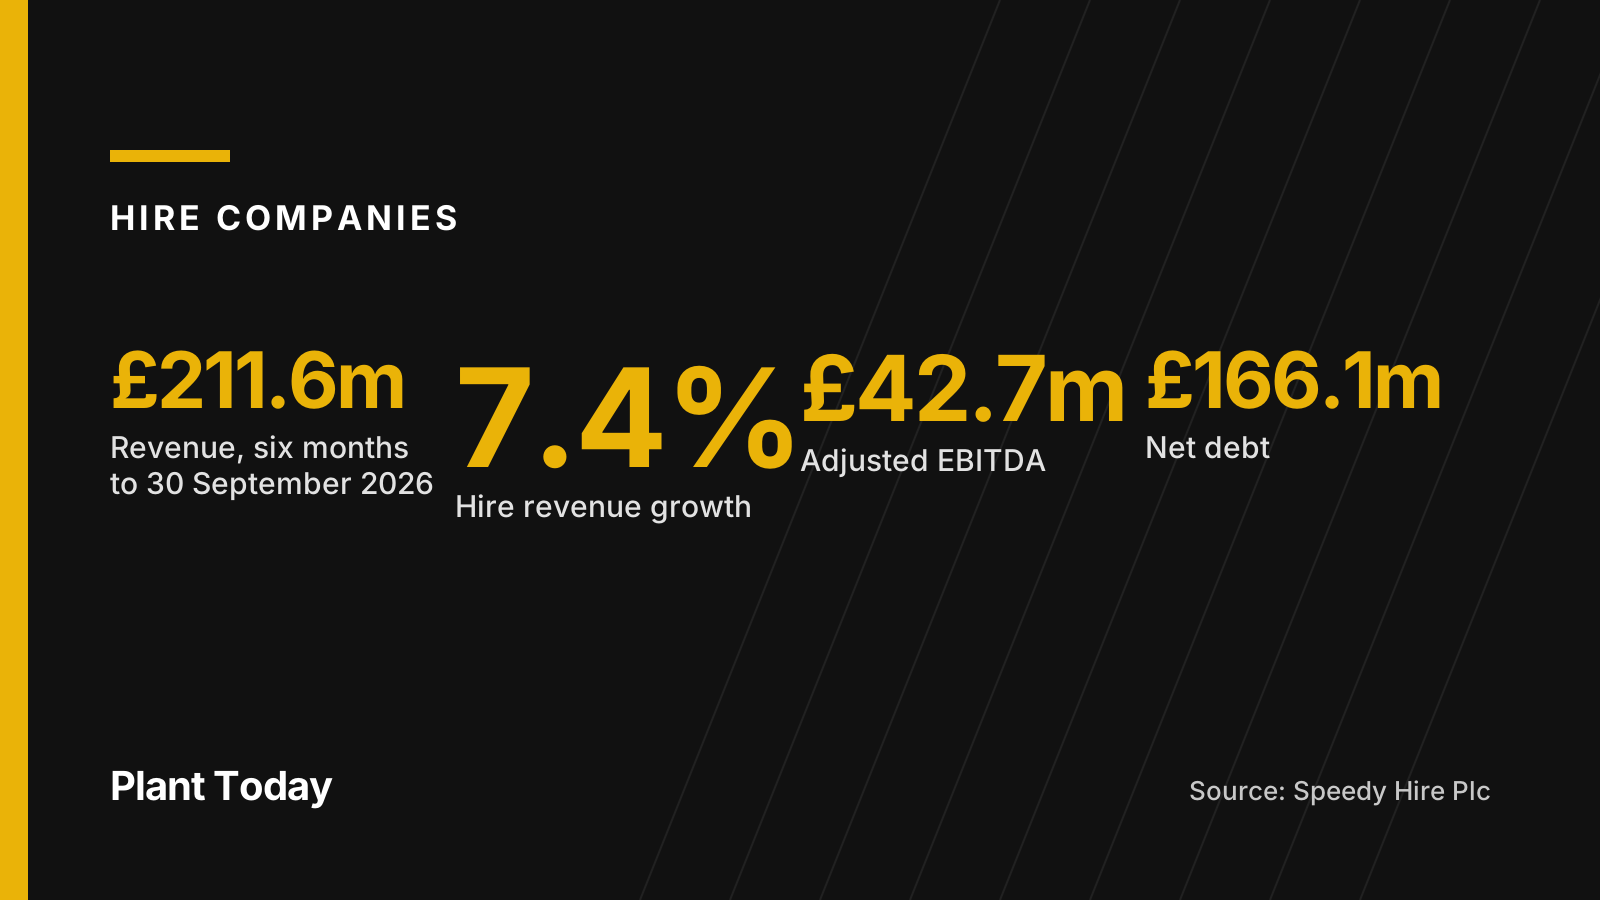
Speedy Hire Plc grew hire revenue by 7.4% in the six months to 30 September 2026 as long-term National customer contracts offset falling volumes among Regional and Local customers, the company said in results published on 18 November.
Group revenue rose 3.1% to £211.6m from £205.2m, against what the company called a subdued market. Excluding planned hire fleet disposals, revenue grew 5.7%, and Speedy Hire said it continued to gain market share.
Adjusted EBITDA rose 10.3% to £42.7m from £38.7m, with margin improving to 20.2% from 18.9%. Adjusted operating profit was £3.7m against £2.1m a year earlier, a 76.2% increase.
Dan Evans, Chief Executive, said: "We are pleased with the strategic and operational progress we have made, delivering growth and gaining market share in a subdued market."
Revenue by business line
Speedy Hire said hire growth came from recently mobilised long-term contracts and National customers, which more than offset continued volume decline across its Regional and Local customer base. Trade and retail growth was constrained by market conditions, it said.
Services revenue excluding fuel rose 0.3%. Within that, Customer Solutions, which includes consumables and training, fell 1.4% because of anticipated lower rates following the ProService agreement. Lloyds British, the group's testing, inspection and certification business, grew 11.4%. Fuel commission revenue rose 27.6%, which the company attributed to higher market fuel prices.
| Revenue line | Change in H1 FY2027 |
|---|---|
| Hire | +7.4% |
| Services (excluding fuel) | +0.3% |
| Customer Solutions | -1.4% |
| Lloyds British TIC | +11.4% |
| Fuel commission | +27.6% |
Disposals revenue fell to £1.9m from £6.9m, which Speedy Hire said was a return to normal levels after the planned divestment of specialist compressors in the prior year.
Debt, cash and dividend
Net debt stood at £166.1m, up from £118.9m, equating to leverage of 3.2 times. The company said it retained adequate headroom within committed facilities.
The adjusted loss before tax was £7.1m, compared with £7.2m a year earlier, which Speedy Hire put down to higher interest costs on higher net debt since the ProService agreement. Statutory operating profit was £1.0m against an operating loss of £5.8m, and the statutory loss before tax narrowed to £9.8m from £15.1m.
Underlying operating cash flow was £38.5m, a 90.2% conversion from adjusted EBITDA, down from £44.6m at 115.2% conversion. Free cash flow was negative £6.9m, compared with a positive £3.7m, due to working capital movements and increased interest, the company said.
The interim dividend is 0.32p a share, up from 0.30p, which Speedy Hire said was in line with a previously guided rebasing of dividends for the period to the end of FY2028.
Contracts and fleet
Speedy Hire said it had more than £132m of multi-year annualised contracts secured with Tier 1 National customers, and that an increased number of secured contracts carried right of first refusal or sole provider status. Recently won long-term contracts had mobilised and were ramping up, although more slowly than expected, as previously announced.
The results describe a well-invested hire fleet alongside a five-year strategic managed fleet partnership agreement with Hilti. In a press release on 28 September 2026, Speedy Hire described the arrangement as acquiring 25,000 Hilti assets under a new rolling five-year agreement, calling it a multi-million-pound investment in new Hilti technology.
Trading under the ProService commercial agreement was described as encouraging, with integration and mobilisation continuing and acceptance rates within target range. Lloyds British testing, inspection and certification services were introduced to the ProService marketplace in October 2026.
Strategy and outlook
Speedy Hire said the 'Enable' phase of its Velocity strategy had concluded, with further benefits to come from the 'Deliver' phase. It said use of data and AI had improved operational efficiency and decision-making.
The company is starting a review of its customer and product portfolio, the level of capital intensity and the profitability of products.
Evans said: "While we expect current market conditions to persist, our expectations for FY2027 remain unchanged. Speedy Hire is well positioned to capitalise as the market recovers and our long-term opportunity remains strong."
Speedy Hire said Regional and Local markets remained challenging. The company opened its first depot in Wigan in 1977.
On the record: Speedy Hire Plc
Sources
- Speedy Hire Plc (RNS via Investegate) (opens in a new tab) (accessed 2026-11-19)
- Speedy Hire Plc (opens in a new tab) (accessed 2026-11-19)
- Speedy Hire Plc (Speedy Services) (opens in a new tab) (accessed 2026-11-19)
This story was researched from the primary sources above and checked against them before publication. Spotted an error? Tell us and we will correct it promptly.